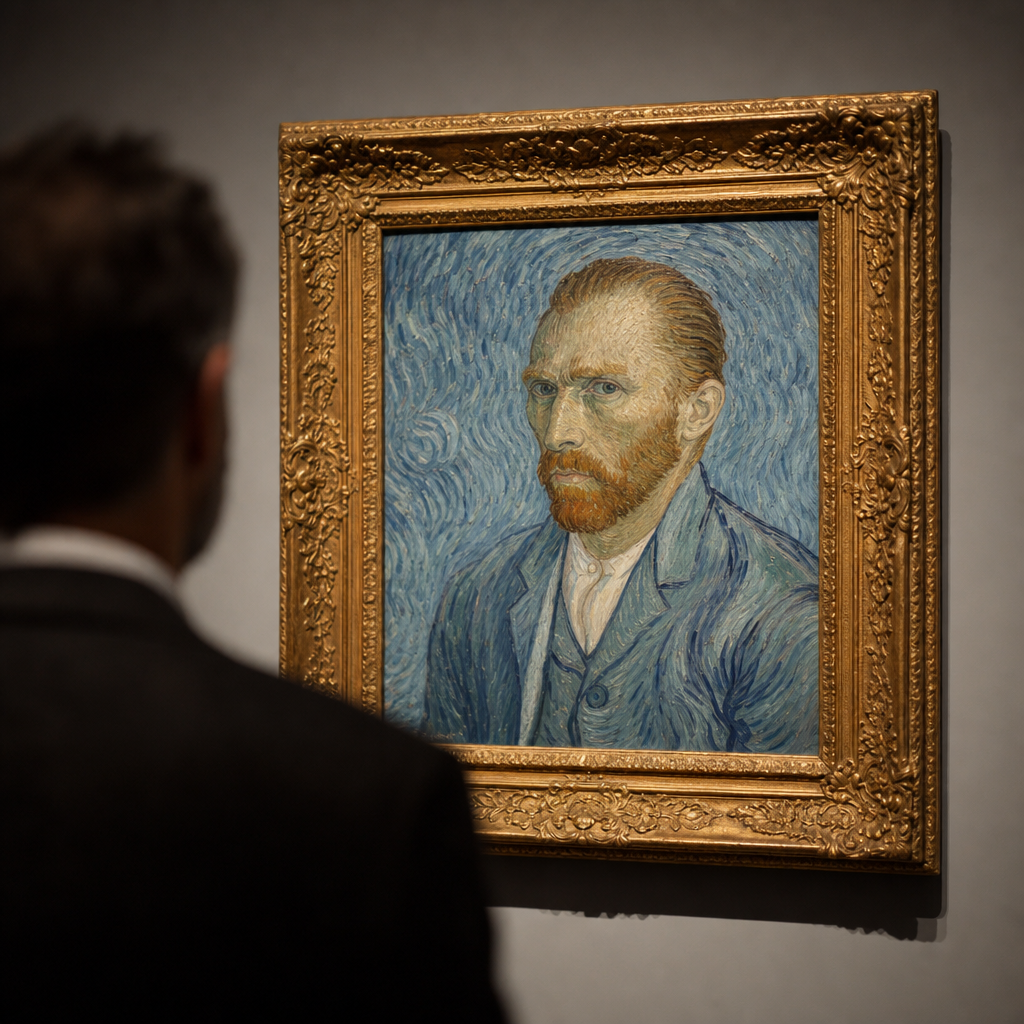
Here is something the auction catalogues never quite spell out: when a painting sells for a serious sum, you are almost never paying for the painting. You are paying for a story – a managed, carefully paced story about a person who can no longer add a single new chapter to it.
That sounds cynical. It is a little. But once you see how an artist's market actually gets made, you cannot unsee it. You will look at any "art as investment" conversation very differently.
Start With Scarcity
Start with scarcity. Property people say location, location, location. The art market runs on scarcity in exactly the same way – except property can be built on. A dead artist cannot produce more work. That fixed supply is the engine of the whole thing. But here is the part that surprises people: scarcity in the art market is not just a natural fact. It is actively managed.
When an artist dies, somebody inherits not just the physical works but control over them. An estate can decide how many paintings come to market in any given year, which ones appear in which sales, and which ones are quietly kept back. Flood the market and prices soften. Release works slowly, selectively, and the sense of rarity holds – or grows. It is supply chain management with oil paint.
How is an artist’s market built?
Demand gets managed too. A major retrospective at a reputable gallery is a cultural event and a financial instrument at the same time. The timing is rarely accidental. A travelling exhibition lands, the critical conversation restarts, collectors who missed the artist the first time around start paying attention. Auction results in the months after a well-placed retrospective can look startlingly different to the months before – the show creates the moment, and the moment lifts the price.
The Auction Guarantee Nobody Discusses
Then there are auction guarantees – perhaps the least-discussed mechanism of all. A major auction house will sometimes guarantee a seller a minimum price before the hammer falls, often underwritten by a third party who gets a cut if the lot does well. This creates a floor. A work cannot visibly fail. And a work that cannot fail looks like a safe bet, which attracts more bidders, which becomes a self-fulfilling result. The guarantee manufactures confidence.
For background on how colour, materials and the physical craft of painting have their own wild histories, The World Was a Paint Factory Before We Built Our Own is worth an hour of your afternoon.
Why does an artist’s career matter more than the work?
What all of this means practically is that buying art as an investment is really a bet on biography. Who manages this estate? Is there institutional interest, museum acquisitions, a body of critical writing? Is the artist in the early stages of reappraisal, or has the market already priced in the mythology? The canvas tells you about the painter's eye. The career arc tells you whether the price is going anywhere.
None of which means art is a bad place to put money. It means the due diligence looks nothing like buying a share, and a great deal like reading a very long, very interesting life.
Questions this raises
- What actually determines a painting's price?
- Can an unknown artist's work appreciate?